
Headlines about Social Security’s finances have become background noise: a trust fund running low, a Congress that hasn’t acted, projections that shift by a year or two with each new report. It would be easy to conclude the program is either doomed or untouchable, and to stop thinking about it altogether until retirement is close.
Neither reaction serves you well — and if you’re in your late 20s through early 40s, the headlines are arguably less important to your planning than a much simpler, decades-old piece of program math that hasn’t changed: waiting to claim still pays.
The Scheduled Benefit Increase for Delaying a Claim
Under current law, a worker born in 1960 or later has a full retirement age (FRA) of 67. Delaying after FRA increases the scheduled monthly retirement benefit by about 8% per year until age 70; claiming at 62 reduces the worker benefit to about 70% of the FRA amount, while claiming at 70 increases it to about 124%.
For illustration, a $2,500 FRA benefit would be about $1,750 at 62 or $3,100 at 70.
These adjustments affect monthly benefits, not an investment return, and actual lifetime value depends on longevity, taxes, other income, household circumstances, and future law. Benefits receive cost-of-living adjustments when applicable; the 2026 COLA was 2.8%.
As of July 29, 2026, the Federal Reserve maintained a 3.5%–3.75% target range, and it described inflation as elevated relative to its 2% goal. Against that backdrop, delaying Social Security can increase scheduled monthly income under current law, but it should not be described as a guaranteed investment return.
The appropriate claiming age depends on health and longevity expectations, cash needs, taxes, employment, marital and survivor considerations, Medicare enrollment, other assets, and the possibility of future legislative change. For someone who retires before claiming, savings used to cover the intervening years can serve as a bridge.
Why This Math Matters at 32, Not Just 62
It can be useful to consider Social Security claiming well before retirement. Funding a taxable brokerage account, HSA, or supplemental retirement account may create flexibility to cover expenses between retirement and a later claim.
Results will depend on contributions, investment selection, market performance, fees, taxes, inflation, account rules, and withdrawals; growth is not assured. Starting earlier generally provides more time to save, while starting later may reduce flexibility, but neither timing nor claiming age is suitable for everyone.
Current interest rates may affect the yield available on cash, short-duration bonds, and certificates of deposit, but these choices are not interchangeable or risk-free. Consider interest-rate, reinvestment, credit, inflation, liquidity, tax, maturity, early-withdrawal, and deposit-insurance-limit risks, as applicable. The federal funds target range is not the yield an investor will necessarily receive.
What the Numbers Look Like
The chart below illustrates current-law mechanics for a worker born in 1960 or later using a hypothetical $2,500 monthly benefit at FRA 67. It is not a projection or recommendation for any individual.
Claiming from age 62 through 67 reduces the monthly amount relative to FRA; delaying after FRA increases the scheduled monthly amount through age 70. Actual benefits and lifetime outcomes vary.
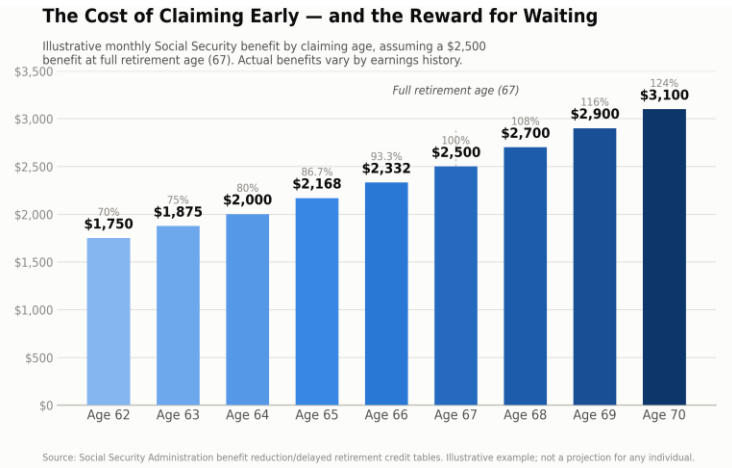
Illustrative monthly Social Security benefit by claiming age, assuming a $2,500 benefit at full retirement age (67). Actual benefits vary by earnings history.
The Spousal Wrinkle Worth Planning For
For married couples, claiming is a household decision. A spouse’s full benefit may be up to 50% of the worker’s FRA benefit; delayed retirement credits earned by the worker do not increase that maximum spousal amount.
Survivor benefits may be based on the deceased worker’s higher benefit, but eligibility and reductions depend on the survivor’s claiming age and other facts.
Delaying the higher earner’s benefit can increase potential survivor protection, but whether that approach is appropriate depends on both spouses’ health, longevity, cash needs, work history, taxes, and other resources.
Plan in Pencil, Not Pen
The 2026 Trustees Report projects that combined OASDI reserves would be depleted in the third quarter of 2034 and that continuing income would cover about 83% of scheduled benefits at that time, absent legislative change.
This is a projection under stated assumptions, not a benefit cliff or a prediction of Congressional action. Congress may change taxes, retirement ages, benefit formulas, or other provisions, but the timing and form of any change are uncertain.
Treat a claiming strategy as a working assumption and revisit it as personal circumstances and the law evolve.
The Bottom Line
You do not need to select a claiming age decades in advance. Building flexible savings may preserve a wider range of future choices, including—but not necessarily favoring—a later claim.
A financial review can compare claiming ages in light of cash flow, asset location, taxes, health, longevity, household benefits, and time horizon. Consider discussing these tradeoffs with qualified financial, tax, and legal professionals and the Social Security Administration.
Key Data Points (2026)
- Full retirement age reaches 67 for those born in 1960 or later.
- 2026 earnings test threshold for early claimants: $24,480/year before FRA; $65,160 in the year FRA is reached.
- 2026 Social Security COLA: 2.8%.
- Delayed retirement credits: approximately 8% permanent benefit increase per year of delay between FRA and age 70.
- Social Security Trustees project combined trust fund reserves depleted in 2034, after which incoming revenue would cover approximately 83% of scheduled benefits absent legislative changes.
Primary Sources
- Social Security Administration — 2026 COLA Fact Sheet
- Social Security Administration — 2026 Trustees Report Highlights
- Social Security Administration — Early or Delayed Retirement Table
- Social Security Administration — Delayed Retirement, Born 1960 or Later
- Social Security Administration — Spouse’s Benefits Guidance
- Federal Reserve — FOMC Statement, July 29, 2026
- FINRA Rule 2210 — Communications with the Public